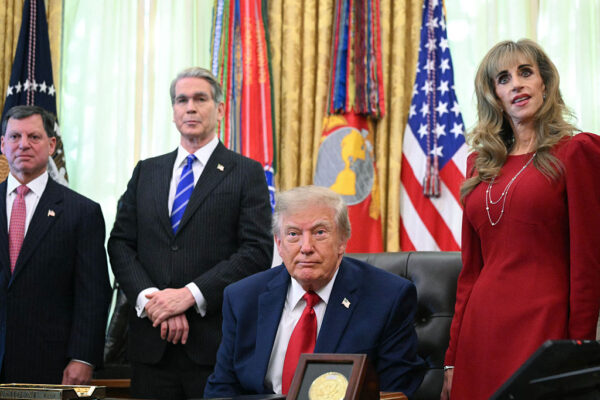
Approximately 60 million American children were automatically enrolled in Trump Accounts by the Treasury Department on Oct. 1, a move President Donald Trump later highlighted as a major milestone in the program. The automatic enrollment reportedly caught some parents by surprise.
Pros and Cons of the Trump Accounts
The automatic enrollment brings the total number of children included in the program to approximately 70 million, including the roughly 10 million accounts previously established by parents and guardians since the initiative launched July 4. The administration said the program covers every American child under 18 with a valid Social Security number.
The program, established under Trump’s One Big Beautiful Bill, provides tax-deferred investment accounts intended to help children accumulate money that can eventually support major financial milestones, including higher education, homeownership, entrepreneurship, and retirement.
However, automatic enrollment does not mean parents can ignore the accounts. Families must still complete the required steps to claim their children’s accounts and access certain financial benefits.
Trump Accounts are tax-deferred investment accounts established in a child’s name. Parents or guardians manage the accounts until the child turns 18, when the funds become subject to the rules governing traditional individual retirement accounts, or IRAs.
The money is invested for long-term growth, with the program initially relying on low-cost funds tracking the S&P 500, an index representing approximately 500 large publicly traded U.S. companies. Under the program’s rules, certain charitable contributions may also include individual company stocks.
Families, friends, and other eligible contributors can deposit up to $5,000 per child annually, subject to program rules. The accounts are not traditional savings accounts, however, and investment returns are not guaranteed. Their value can fluctuate with the stock market.
More than $4.5 billion had been deposited into Trump Accounts by the time of the White House‘s Oct. 7 announcement. That total included approximately $1.3 billion in federal seed money, $2.6 billion in philanthropic contributions and more than $600 million from family members and friends, according to the administration.
Although all eligible children under 18 with valid Social Security numbers can receive accounts, not every child qualifies for the same initial contribution.
Children born between Jan. 1, 2025, and Dec. 31, 2028, are eligible for a one-time, tax-free $1,000 contribution from the federal government when their accounts are properly claimed and activated.
Billionaire philanthropists Michael Dell, founder of Dell Technologies, and his wife, Susan Dell, pledged $6.25 billion to fund $250 contributions for approximately 25 million children. The initiative targets children born between 2016 and 2024 who live in ZIP codes where the median family income is $118,000 or less. Children living on military bases also qualify under the program’s eligibility rules.
Concerns have also emerged over rules allowing charitable donations of individual company stocks. Critics argue that concentrating a child’s investments in a single company could expose the account to greater risk than a diversified index fund. They have also raised questions about potential conflicts of interest, stock-price effects and tax benefits for wealthy donors.
Despite their potential to help children build long-term wealth, Trump Accounts come with several limitations parents should understand before contributing.
One major drawback is that funds generally cannot be accessed before the beneficiary turns 18, making the accounts unsuitable for immediate family emergencies, medical expenses, or K-12 education costs.
Withdrawing funds early may trigger income taxes and penalties, depending on the circumstances.
Trump Accounts offer some tax advantages, but family contributions have limits. Unlike contributions to 529 college savings plans, which may qualify for state tax deductions or credits, individual contributions to Trump Accounts of up to $5,000 annually are not tax-deductible, though investment growth is tax-deferred.
Investment options present another concern. During the growth period, Trump Accounts are limited to qualifying, low-cost mutual funds or exchange-traded funds (ETFs).
And, financial policy experts have questioned whether the program adds unnecessary complexity to an already crowded landscape of savings options. Critics argue that wealthier families may benefit disproportionately because they have more money available to make additional contributions.
There was backlash online as well.
One X user posted: “Trump accounts are just a grift, trump will drain every account at some point and picket the money. He’ll claim it his because it’s in his name.
IT’S A GRIFT”.
Another wrote, “Trump Accounts sounded like an inoffensive idea, even with Trump’s name on them. Michael Dell donated $6 billion to them, but now they’ve turned into a scam for billionaires to unload overvalued stocks.”


